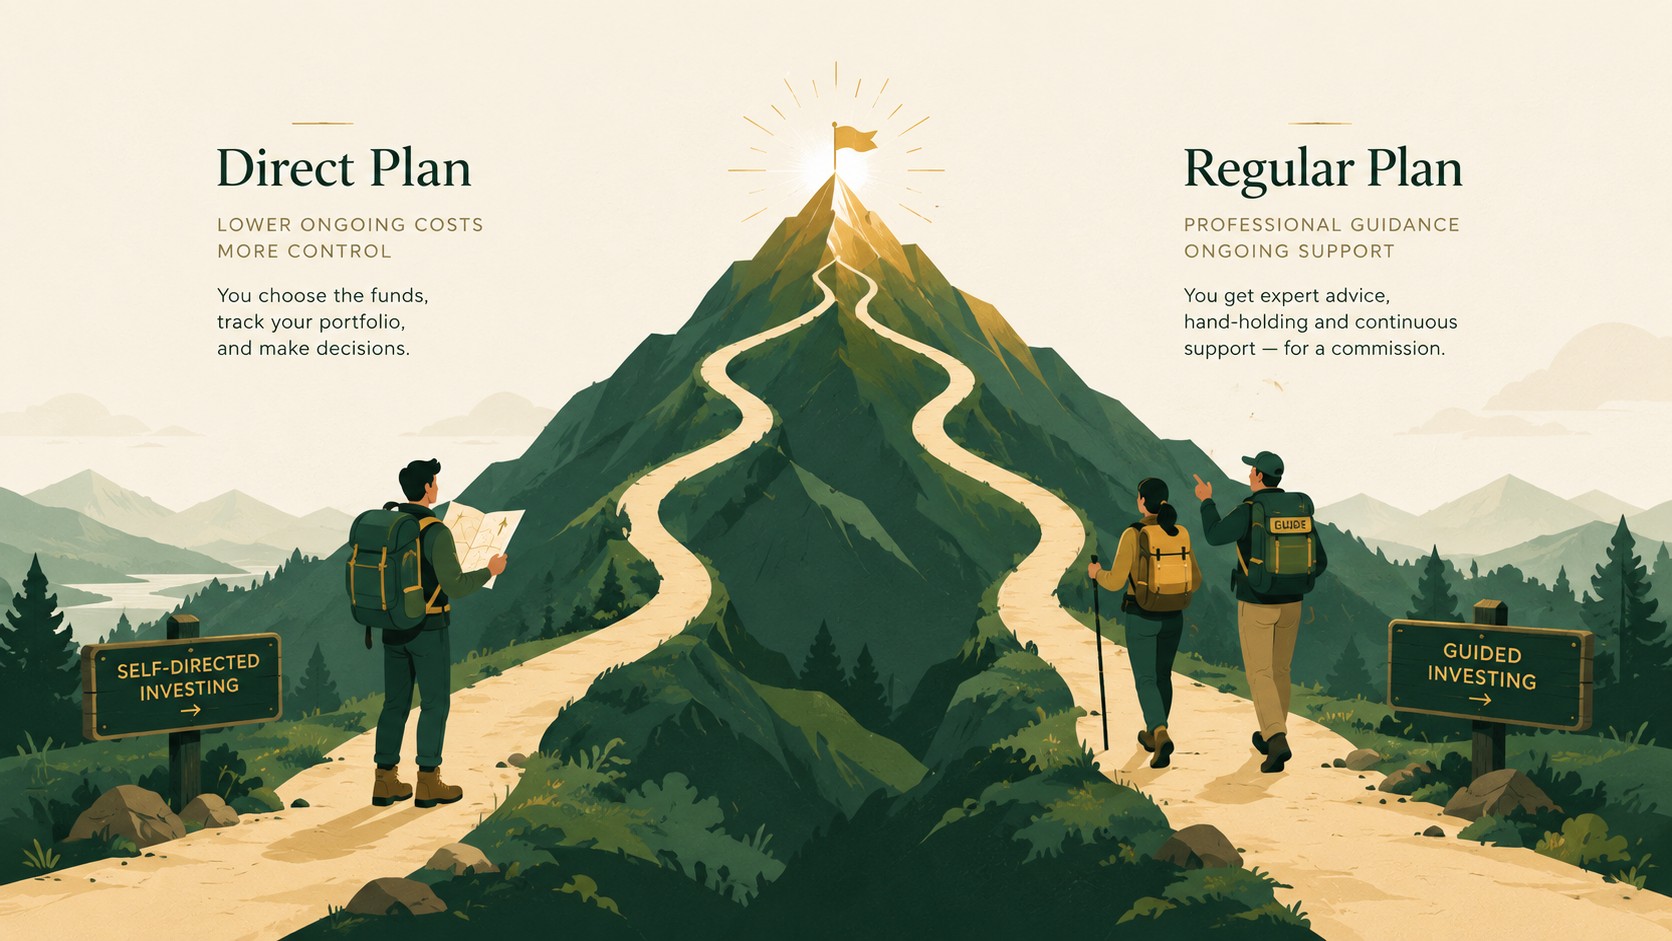
Two plans, same underlying fund
Every mutual fund scheme is typically available in two variants: Direct and Regular. Both invest in the exact same underlying portfolio, managed by the same fund manager, following the same strategy. The only structural difference is how you access the fund.
What actually differs
A Regular plan includes a distributor commission built into its expense ratio - this is what compensates a distributor like Artha Vridhi for the guidance, servicing, and support provided around your investments. A Direct plan excludes that commission, which is why its expense ratio is slightly lower and its NAV, over time, tends to be marginally higher for the same fund.
So which is “better”
That depends entirely on what you value. If you’re confident selecting funds, monitoring your portfolio, handling paperwork, and staying disciplined through market swings entirely on your own, the lower cost of a Direct plan is a genuine, real advantage.
If you’d rather have a distributor helping with fund selection, KYC and paperwork, consolidated tracking across your investments, and someone to talk to when markets get volatile and the instinct is to panic-sell - that support has a cost, and Regular plans are how it’s paid for.
Neither is a trick. It’s a trade-off between a slightly lower ongoing cost and ongoing hand-holding, and reasonable people land on either side of it depending on their own situation.
One thing to be clear about
The commission structure doesn’t change what the fund itself does - its portfolio, strategy, and risk profile are identical either way. It only changes the expense ratio and, correspondingly, the NAV path over time.