The basic idea
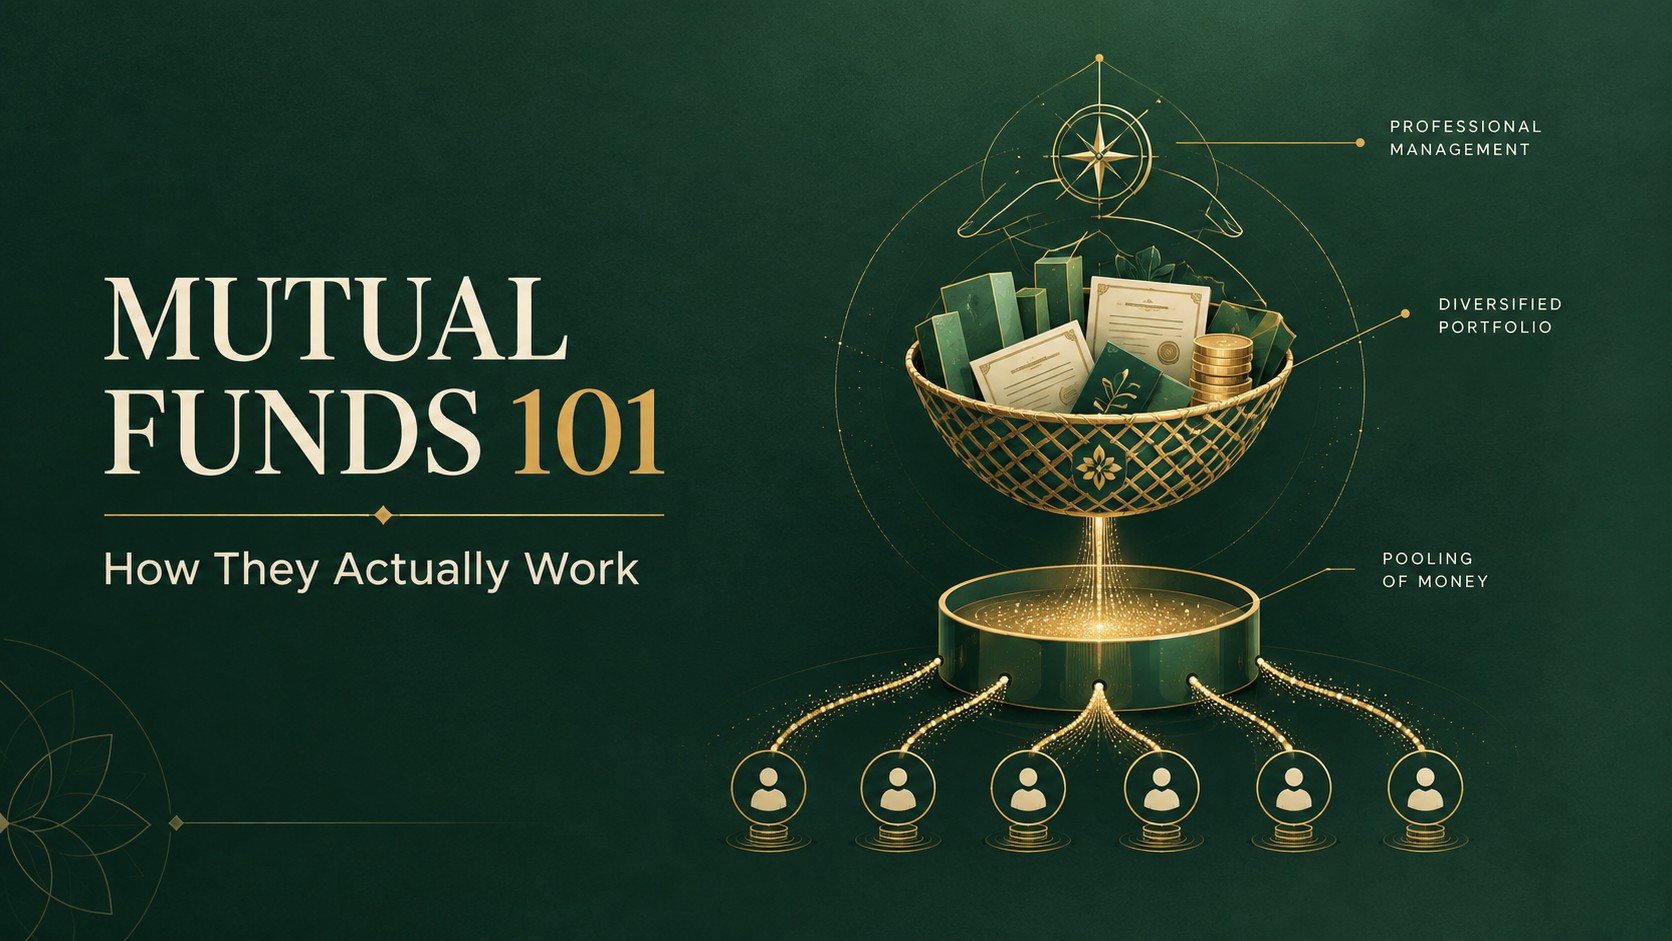
A mutual fund pools money from many investors and uses it to buy a basket of securities - stocks, bonds, or a mix of both - depending on the fund’s stated objective. Instead of picking individual stocks yourself, you own a small slice of that entire basket.
A professional fund manager decides what goes in and out of the basket, within the rules laid out in the fund’s offer document. You don’t manage any of that day to day - you just hold units.
What is NAV, really
Net Asset Value (NAV) is simply the per-unit value of everything the fund holds, updated once a day. If the fund’s total holdings are worth more today than yesterday, NAV goes up. It’s a reflection of the underlying assets, not a score the fund is trying to hit.
A common early confusion: a “cheaper” NAV isn’t a bargain, and a “expensive” NAV isn’t overpriced. Two funds holding identical stocks in identical proportions will always deliver you the same percentage return, whether one has an NAV of ₹10 or ₹1,000.
Where the pooling actually helps
- Diversification - your money is spread across many securities instead of concentrated in one or two picks.
- Professional oversight - someone is tracking the portfolio full-time, which most individual investors realistically can’t do alongside a job.
- Access at small amounts - you can start with a SIP as low as ₹500 a month, something that wouldn’t be practical buying individual securities.
What this doesn’t mean
None of this makes returns predictable or guaranteed - mutual fund investments are market-linked, and value can go down as well as up. The point of understanding the mechanics isn’t to remove risk, it’s to make an informed decision about how much of it you’re comfortable taking on, and in which kind of fund.